Falling prices could trip agents up under NSW underquoting rules
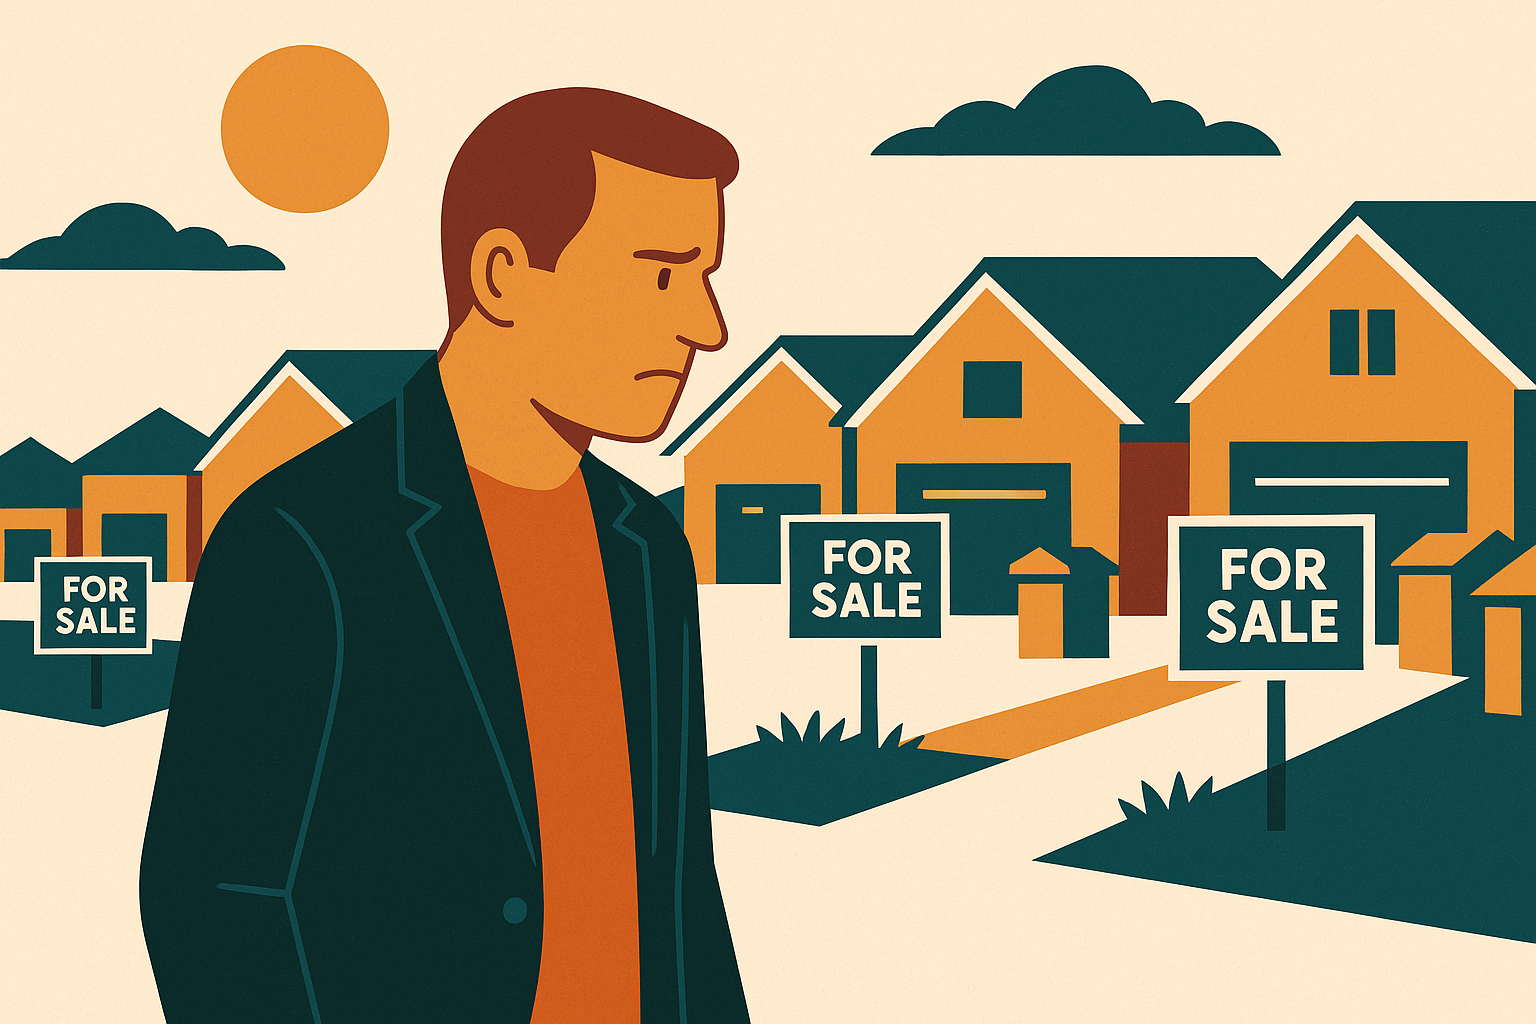
Property experts have flagged a risk that vendors who reject an offer then revise their price guide down in a softening market could breach underquoting laws.
Agents and vendors face a compliance risk under New South Wales underquoting laws when prices fall mid-campaign, according to discussion on the Property Buzz podcast.
Liam Garman said former REIA president and Laing+Simmons chief executive Leanne Pilkington had raised the issue this week, and that the laws carry a degree of opacity that matters more in a market heading down than up.
He set out the scenario. A vendor believes their home is worth $1.1 million, the agent advises $1 million, and the property is listed at $1 million. An offer of $1.05 million comes in and is knocked back because the vendor thinks it is worth more.
Months pass, circumstances change, and the vendor now has to sell into a weaker market where $950,000 is the ceiling.
"If you revise it down, this is just what a few property experts have flagged, to now 900, but you had an offer over that, say that 1 million to 50, that you are now breaking under quoting laws because you've entertained offers that you've turned down and now you've dropped them online," Garman said.
He stressed the point was not guaranteed and was not legal advice, and said the issue would likely be ironed out. "Perhaps you might be fine if people like, well, the market's gone down heaps, there's not much you can do," he said.
Victoria's reserve price disclosure
Garman also pointed to new auction rules coming in Victoria requiring vendors to publicly disclose their exact reserve price, a measure he said had split the industry.
One camp considers it bad for the sector. The other argues it suits current conditions.
"It's a buyer's market at the moment and a lot of agents out there have a lot of listings. They can't get the listings off their hands," Garman said. Listings are sitting "for days and days and days, weeks and weeks and months and months".
Under that view, a disclosed reserve filters the inquiry pool. "At least if you had a publicly disclosed reserve price, the people that are inquiring are going to be the real deal and it will actually help the transaction of property," he said.
Garman said agents were telling him that getting anyone through an open home at all was tough. "Maybe honesty, transparency, maybe that is the policy forward because at least then we can start rebuilding that trust and you'll only have serious buyers."
Buyer frustration behind the rules
Host Phil Tarrant said the rules had grown out of genuine consumer frustration with the transaction process.
He described the common complaint: buyers save, find a property quoted at $600,000, then watch bidding open at $650,000. "I'm emotionally invested, I've seen ourselves in it, we're going to get this," he said. "It can be hugely frustrating."
But Tarrant argued the broader pattern across state, federal and local government has been to make transacting real estate harder, with property management adding another expanding layer of rules.
He contrasted the local experience with Dubai, where he said a business can be set up over a text message. "Good luck even trying to get a permit to put two more seats out the front of your cafe," he said.
Tarrant said the compliance burden was a productivity problem in itself, because small businesses "need to spend so much time, money and effort on keeping to these onerous and draconian rules".
Input costs under the spotlight
Garman raised cement and concrete pricing as another regulatory cost flowing through to housing, saying emissions trading obligations had pushed up production costs that are then passed on. He flagged that he could not verify the scale of the increase and urged listeners to check it themselves.
He argued that if construction materials are running well above where they otherwise would be, that is anchoring inflation higher, noting food and fast-moving consumer goods were sitting at about 3.3 per cent against a headline figure of 4.6 per cent.
"That is something that can be done immediately," he said, advocating tax cuts higher up the supply chain rather than on personal income.
Listen to the full episode: Is Australia heading for a French-style debt crisis?